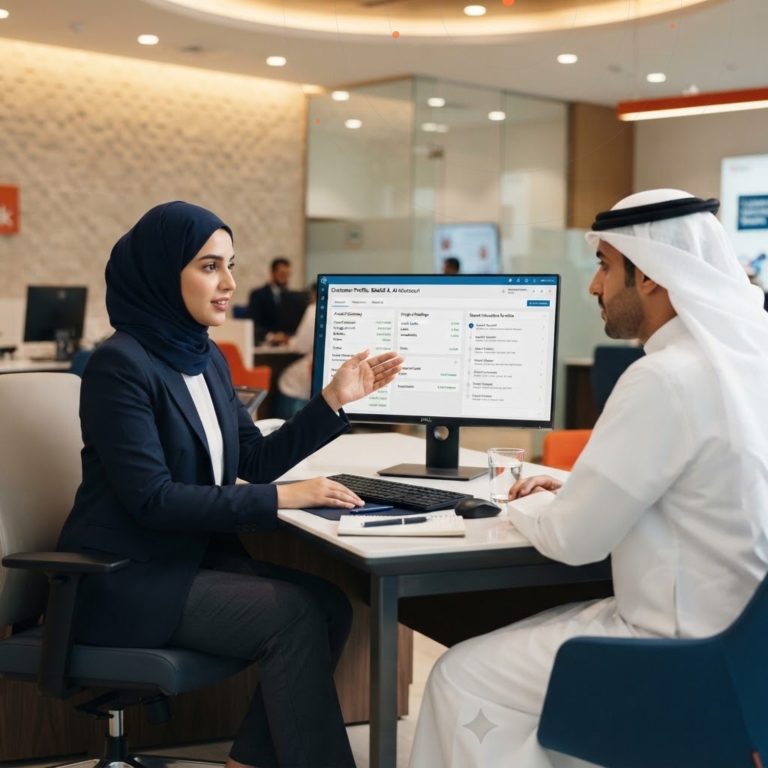

A retail bank customer might hold a current account, a mortgage, a credit card, and an investment product — each potentially opened at a different branch, through a different channel, years apart. A generic sales CRM built around a single, relatively short deal cycle doesn’t naturally represent that kind of long-running, multi-product relationship. That mismatch is exactly why banking CRM exists as its own category rather than banks simply adopting whatever CRM works well for a retail or B2B sales team.
Customer relationship management in banking has to account for regulatory obligations most industries never encounter, a much longer relationship horizon, and a customer who interacts with the institution across branches, call centers, mobile apps, and relationship managers — often simultaneously. This is a look at what makes banking CRM genuinely different, what a serious banking CRM needs to do well, and where the market and the technology are heading in 2026.
What Makes Banking CRM Different From General CRM
The starting difference is regulatory. A banking CRM has to support know-your-customer (KYC) and anti-money-laundering (AML) requirements, maintain detailed audit trails on data access and changes, and handle customer data with a level of security and access control that a generic sales CRM typically wasn’t designed for. Compliance isn’t a nice-to-have layered on afterward — in banking, it has to be structurally part of how the CRM handles data from day one.
The second difference is relationship duration and complexity. A typical B2B sales CRM is built around a discrete deal that closes and moves to a “won” state. A banking relationship doesn’t really close — a customer’s mortgage, savings account, and credit card exist simultaneously and evolve over years or decades, which means the CRM needs to represent a genuinely relational, multi-product view of a customer rather than a pipeline of individual transactions. A relationship manager needs to see the full picture — every product, every service interaction, every risk flag — in one place, not stitched together from separate systems.
Third, the channel mix is unusually wide. A bank customer might open an account in a branch, apply for a loan through a mobile app, and call a contact center about a dispute — and expects the institution to have full context regardless of which channel they used last. Stitching that together consistently is a harder integration problem in banking than in most other industries, simply because core banking systems, digital banking platforms, and CRM often come from different vendors with different data models.
What a Serious Banking CRM Actually Needs to Do
Beyond the baseline CRM functions — contact and account management, case tracking, task automation — banking-specific CRM evaluations consistently point to a specific set of capabilities a general CRM checklist wouldn’t necessarily surface. Real-time data insights matter more here than almost anywhere else, since a relationship manager making a lending or cross-sell decision needs current account and risk data, not a report that refreshed overnight. AI-driven automation reduces the manual follow-up and approval routing that otherwise consumes a relationship manager’s day. Predictive analytics help anticipate a customer’s next need — flagging, for example, a customer whose transaction pattern suggests they’re ready for a different account tier or credit product. Deep integration with core banking systems is non-negotiable, since a CRM disconnected from actual account and transaction data is of limited use to a banker making a real-time decision. And increasingly, open banking API integrations let a CRM pull in data from a customer’s other financial relationships (with consent), giving a fuller financial picture than the bank’s own systems alone would show.
The Market Is Growing Because the Pressure Is Real
The numbers reflect how seriously banks are taking this. The global banking CRM software market was valued at roughly $21.22 billion in 2026, and is projected to reach $40.18 billion by 2030 — a compound annual growth rate above 17%, which is a rapid expansion for enterprise software of any kind. The driver isn’t abstract digital transformation ambition; it’s competitive pressure. Fintech and digital-only banks have set customer expectations for personalized, real-time, mobile-first service, and traditional banks with decades of legacy infrastructure are under direct pressure to match that experience without the benefit of starting from a clean slate.
Microsoft’s Approach: Dynamics 365 Plus an Industry Layer
For banks already invested in the Microsoft ecosystem, Dynamics 365 provides the underlying CRM engine — Sales, Customer Service, and Customer Insights — while Microsoft Cloud for Financial Services adds an industry-specific layer on top: pre-built compliance tooling mapped to financial-sector regulatory requirements, reference architectures built specifically for banking workloads, and industry templates covering scenarios like mortgage document processing. Microsoft’s compliance program spans over 100 compliance offerings, positioned as the most extensive among major cloud providers, alongside tools like Microsoft Purview for the data governance and risk management work that banking regulators specifically expect to see. That combination — a genuinely capable general CRM engine plus an industry compliance and architecture layer — is a meaningfully different proposition than adopting a generic CRM and building banking-specific compliance controls entirely from scratch.
Where Banking CRM Actually Gets Used
In practice, banking CRM shows up across several concrete scenarios: relationship banking teams managing high-value commercial or private banking clients who expect a single point of contact with full visibility into every product they hold; retail cross-sell and next-best-offer programs that use a customer’s existing product mix and transaction behavior to surface relevant new products rather than generic mass marketing; digital onboarding flows that need to move a prospective customer from initial inquiry through KYC verification to an opened account without losing them to friction along the way; and wealth management teams tracking client goals, risk tolerance, and portfolio conversations over long advisory relationships. Each of these scenarios shares the same underlying need — a complete, current, compliant view of the customer — even though the day-to-day workflow looks different across them. A bank running a mature CRM implementation typically finds these use cases reinforce each other over time: better onboarding data improves cross-sell targeting, which in turn gives relationship managers more relevant context for the next client conversation.
Islamic Banking Adds Another Layer of Complexity
Bahrain and much of the GCC operate a dual banking system, with conventional and Islamic banks serving customers side by side, and for Islamic financial institutions specifically, a banking CRM needs to represent products and customer relationships that don’t map cleanly onto conventional banking templates — Murabaha, Ijara, and Sukuk-based products, for instance, structure the customer relationship differently than a conventional loan or credit facility does, and a CRM built entirely around conventional banking assumptions can end up forcing an awkward, imprecise fit for Sharia-compliant product lines. A CRM implementation partner without prior Islamic banking experience often misses this until well into a project, which is a genuinely avoidable problem if the requirement is surfaced during discovery rather than after configuration is already underway.
Data Security as a First-Class Requirement, Not an Add-On
Banking customer data is about as sensitive as CRM data gets — account numbers, transaction history, income and credit information, identity verification records — which means security architecture has to be considered from the earliest design decisions rather than bolted on before go-live. Role-based access controls need to be genuinely granular, since a call center agent, a branch relationship manager, and a compliance officer legitimately need very different views into the same customer record. Encryption at rest and in transit, detailed access logging for every record view or change, and regular security auditing all need to be built into the CRM configuration itself, not left to a separate security team to retrofit after the platform is already live and holding real customer data.
Compliance and Trust Considerations for GCC Banks
For banks operating in Bahrain and across the GCC specifically, regional regulatory requirements from bodies like the Central Bank of Bahrain add another layer to what a banking CRM needs to support, alongside broader considerations like data residency and Arabic-language customer service. A CRM implementation for a bank in this region isn’t just a technical configuration exercise — it requires understanding what regional regulators expect from customer data handling and audit trails, and building the CRM’s compliance controls around those specific requirements rather than a generic Western regulatory template.
Getting Started
Banking CRM implementations carry more risk than a typical CRM project, precisely because of the compliance, integration, and data-sensitivity factors covered above — which makes the right implementation partner even more important than in a lower-stakes industry.
Global ITS works with financial institutions across Bahrain and the GCC to plan and implement CRM systems that meet both the customer-experience goals and the regulatory realities specific to banking in this region — including conventional and Islamic banking product structures, regional compliance expectations, and the security architecture decisions that need to be right from the start rather than corrected after launch. Contact our team to talk through what a banking CRM implementation would involve for your institution, or request a live demo to see the platform in action.