
A standard investment management platform is built around a clean assumption: positions have a daily market price, data arrives from a custodian in a predictable format, and performance can be calculated straightforwardly from that price series. Alternative investments break that assumption at every point. Private equity, venture capital, private credit, hedge funds, and real estate don’t trade daily, don’t report through standard custodian feeds, and often don’t have a market price at all between formal valuation events — which is exactly why managing them well requires alternative investment management software built around a fundamentally different set of problems than a public-markets platform ever has to solve.
This is a look at what genuinely distinguishes alternative investment management software, the specific data and valuation challenges it needs to handle, and what to weigh when evaluating a platform for this asset class.
The Data Problem Alternative Investments Create
Alternative asset classes generate data through an entirely different pipeline than public securities. Rather than a daily custodian feed, alternative investment platforms need to consolidate information from fund administrators, general partners, and hundreds of global custodians, automatically extracting figures from capital call notices, distribution notices, NAV statements, and private market documents that arrive as unstructured PDFs rather than clean data files. A platform genuinely built for this category tracks dozens of distinct alternative asset types at a granular level — private equity, hedge funds, venture capital, real estate, private credit, and structured notes each carry their own data structure and reporting cadence, and treating them as one generic “alternatives” bucket loses the detail that actually matters for portfolio-level decisions.
This data fragmentation is the single biggest operational drag in alternative investment management, and it’s precisely the problem general-purpose portfolio software isn’t built to solve. Manual reconciliation across fragmented documents and disconnected spreadsheets remains the default workflow at many firms, which slows every downstream reporting cycle and introduces exactly the kind of error risk that a purpose-built platform is designed to eliminate.
Valuation Is Fundamentally Different Without a Daily Market Price
Where public securities are valued continuously by the market, alternative investments require periodic, often manual or third-party valuation — and the software supporting that process needs to handle return calculations that account for irregular cash flow timing rather than a simple price series. Internal rate of return and time-weighted return calculations, computed transparently and auditable back to their underlying cash flows, are core requirements rather than optional add-ons for this asset class. For private credit specifically, valuation software increasingly uses AI to extract critical terms directly from credit agreements and compliance documents — covenant monitoring thresholds, debt service coverage ratios, cross-default clauses — with extraction accuracy reported around 99% for well-trained models, turning what used to be a laborious manual document review into a fast, structured data pull.
The operational payoff of getting this right is substantial: firms adopting AI-driven data extraction for private credit and other alternative asset documentation report eliminating up to 90% of the manual data entry work that used to consume analyst time, freeing that capacity for actual portfolio analysis rather than document processing.
Entity Complexity Is the Default, Not the Exception
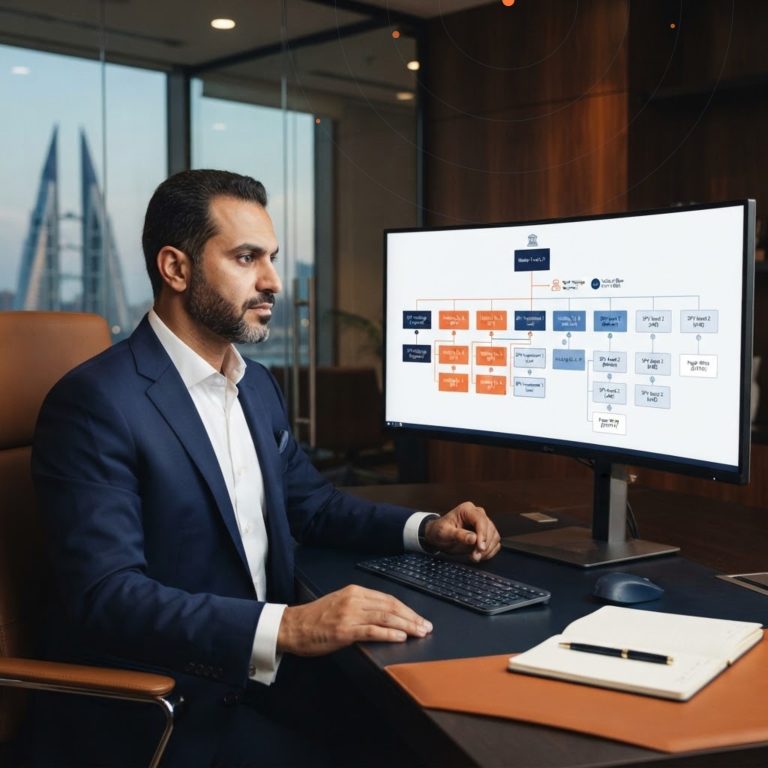
Alternative investment structures routinely involve multiple layered entities — a fund investing through special purpose vehicles, co-investment structures alongside a main fund, and holding companies interposed for tax or regulatory reasons. Software built for this category needs to provide complete visibility across every entity, owner, asset, and liability in that structure, with interactive mapping that lets a portfolio manager or investor trace how a consolidated figure was actually built rather than accepting it as a black-box output. This is a materially higher bar than the entity handling most general investment platforms are built for, and it’s one of the clearest signals of whether a platform was genuinely designed for alternatives or adapted from a public-markets base.
Monitoring Risk Without Daily Price Signals
Public markets risk management leans heavily on daily price volatility and correlation data — tools that simply don’t exist for most alternative holdings. Alternative investment platforms instead need to track financial, operational, and increasingly ESG metrics reported periodically by portfolio companies or general partners, combined with scenario forecasting that models how a private holding might perform under different conditions in the absence of a continuous market signal. This kind of monitoring depends entirely on the document extraction and data consolidation described earlier — a platform that can’t reliably pull structured data from GP reports and portfolio company financials can’t support meaningful risk monitoring on top of it, no matter how sophisticated its analytics layer looks on paper.
Benchmarking Without a Public Comparable
One of the harder problems alternative investment platforms need to solve is performance benchmarking, since there’s rarely a clean public index to compare a private equity fund, a piece of direct real estate, or a private credit position against. Rather than defaulting to a loosely related public market index, a genuinely capable platform supports benchmarking against vintage-year peer groups, custom blended benchmarks built from a firm’s actual allocation mix, and public-market-equivalent calculations that translate a private investment’s cash flows into what an equivalent public market investment would have returned over the same period. Without this kind of purpose-built benchmarking, a firm is left comparing alternative performance to a benchmark that doesn’t actually reflect the risk or liquidity profile of what it’s measuring, which tends to produce misleading conclusions in exactly the reviews — board meetings, investment committee updates — where accuracy matters most.
The category’s growth reflects how central this infrastructure has become as institutional and family office allocations to alternatives keep expanding: the alternative investment management software market is forecasted to grow from roughly $0.91 billion in 2026 to $2.6 billion by 2035, an 11.19% compound annual growth rate — nearly tripling over the forecast period as more firms move away from spreadsheet-based alternatives tracking toward dedicated platforms.
Reporting That Meets Institutional Investor Expectations
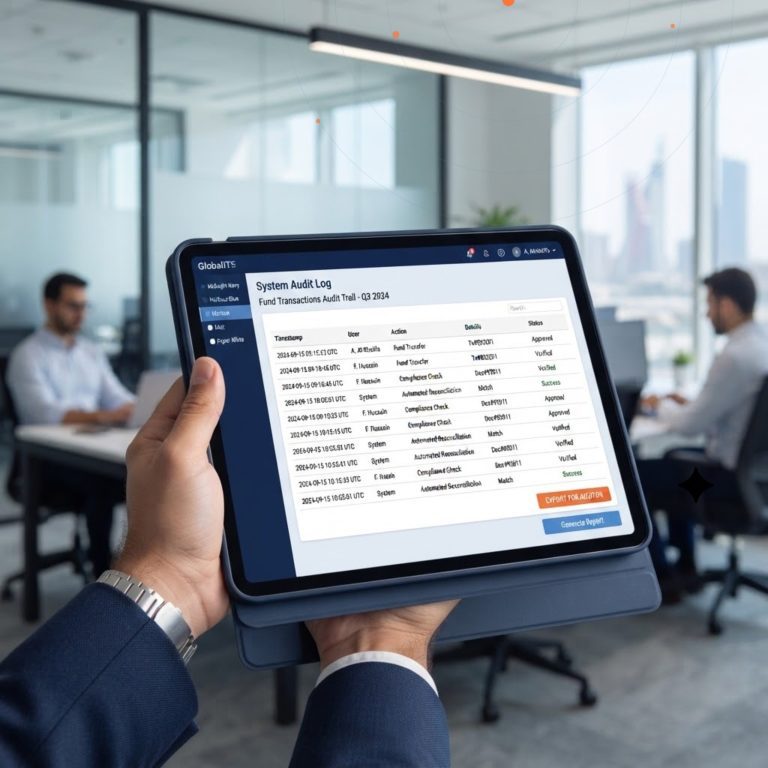
Institutional investors and family offices allocating to alternatives expect reporting depth that matches what they’d get from a public markets manager, even though the underlying data is inherently messier. A mature alternative investment platform should support well over a hundred prebuilt report types spanning performance, liquidity, expenses, risk, and tax reporting, generated from the same reconciled data feeding the rest of the platform rather than assembled separately for each investor request. Audit-ready valuations, produced quickly enough to meet both investor transparency expectations and regulatory scrutiny, are increasingly the baseline expectation rather than a differentiator — a platform still measuring its valuation cycle in weeks is falling behind what both investors and regulators now expect.
Evaluating a Platform: What Actually Separates the Purpose-Built From the Adapted
When comparing alternative investment management software, the clearest signal of whether a platform was genuinely built for this asset class or adapted from a public-markets base is how it handles the unstructured document problem specifically. Ask a vendor directly how their platform extracts data from a real capital call notice or GP quarterly report — not a cleaned-up sample document, but an actual PDF from a fund administrator a firm currently works with — and watch how confidently they answer. A platform with genuine AI-driven extraction built for this category will demonstrate it readily; one relying on manual data entry behind the scenes tends to deflect toward a services team that “handles that for you,” which is a materially different and more expensive proposition once the relationship scales past a handful of positions.
Total cost of ownership for alternative investment platforms deserves particular scrutiny because pricing models in this category vary widely — some charge per tracked position or asset, others by assets under management, and others bundle data extraction and reconciliation as a paid service layered on top of the core software license. A firm with a genuinely large and complex alternatives allocation should model cost growth against its own expected position count over the next several years, not just the current portfolio, since a pricing model that looks reasonable today can scale poorly as a program grows.
Evaluating Alternative Investment Software for a GCC-Based Firm
For family offices, sovereign-adjacent investors, and asset managers in Bahrain and the wider GCC allocating meaningfully to alternatives, evaluate a platform’s actual breadth of asset-type coverage against the specific mix the firm holds — a platform strong on private equity and venture capital but weak on real estate or private credit data structures will leave gaps precisely where a diversified GCC alternatives allocation is likely to concentrate. Multi-currency and cross-jurisdictional reporting matters here as much as in any other category covered in this series, and it’s worth confirming a platform’s document extraction has been tested against the specific formats regional fund administrators and GPs actually use, not only US and European document conventions.
Managing Complexity Without Managing It Manually
Global ITS works with family offices, asset managers, and institutional investors across Bahrain and the GCC to implement alternative investment management software built for the data, valuation, and entity complexity this asset class actually involves. Contact our team to talk through your current alternatives data and reporting setup, or request a live demo to see the platform handle it directly.